Africa is not one market. Understanding the differences is not only a way to control downside. It is also the starting point for identifying opportunities that broad generalisations can leave underappreciated.
When analysing Europe, investors do not treat Switzerland, Germany, Greece and Romania as the same market. They differ in currency regimes, fiscal positions, institutions, sector composition, market depth and political risk. Yet Africa is still frequently discussed as though a single label could describe an entire continent.
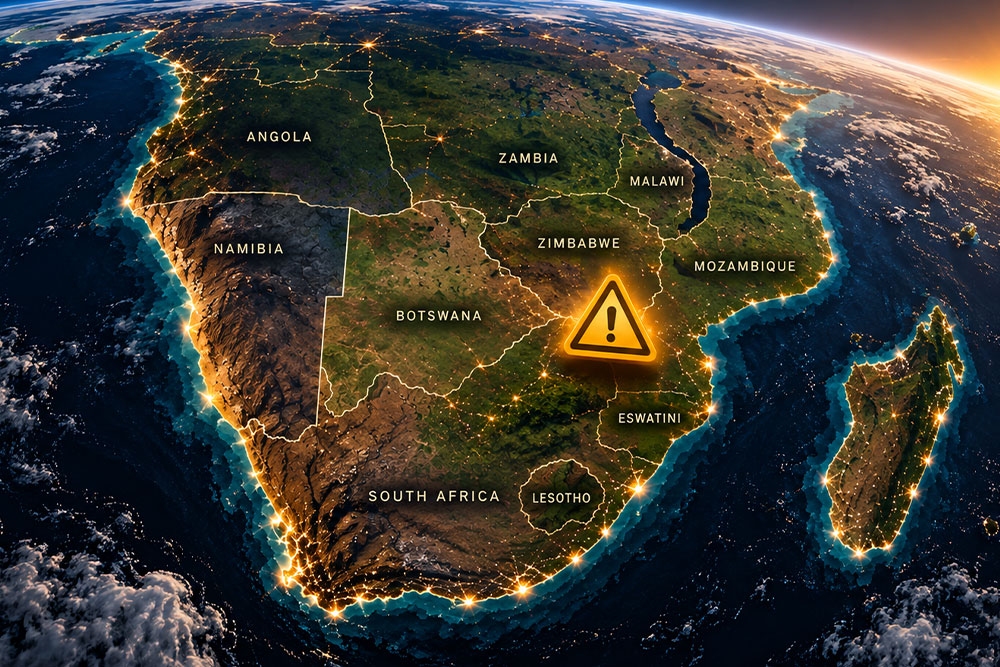
That simplification is one of the main analytical obstacles to investing in Africa. The continent comprises 54 countries, five broad macro-regions and more than 30 exchanges. It combines different currencies, capital markets, fiscal profiles, political systems, growth models and levels of liquidity. A headline about one country can shape perceptions of the whole continent even when the underlying economic and financial links are limited.
For investors, this heterogeneity is not a side issue. It determines what can be owned, how positions can be sized, how quickly they can be exited, which risks need to be hedged and, ultimately, where structural growth can translate into investable earnings.
Africa is often approached through continent-wide statistics: population, GDP growth, natural resources or urbanisation. These measures are useful for understanding the scale of the long-term theme, but they are insufficient for implementation. The same demographic trend can produce very different outcomes depending on institutions, access to capital, infrastructure, currency stability and the depth of local financial markets.
The result is a continent in which high-growth economies can coexist with shallow exchanges, mature capital markets can sit alongside slower macro growth, and resource-rich countries can remain difficult to access through public equities. Country selection therefore becomes part of the investment thesis rather than a final portfolio-construction step.
Northern Africa is increasingly connected to European and Mediterranean supply chains. Morocco and Egypt offer some of the region’s deeper listed-market access and relatively diversified economic structures, with exposure across manufacturing, financial services, energy, tourism, telecoms, consumer activity and infrastructure.
The investment angle is therefore different from a pure frontier-market narrative. In Morocco, industrial development and regional trade integration support a broadening corporate base. Egypt combines significant domestic scale with a large and diversified economy. At the same time, investors must remain sensitive to foreign-exchange conditions, fiscal dynamics and geopolitical developments. The opportunity can be meaningful, but the macro backdrop matters materially for valuation and liquidity.
West Africa is shaped more directly by demographics, consumer growth, banking, fintech, telecoms and hydrocarbons. Nigeria provides exceptional scale through Africa’s largest population and one of its most important financial and consumer markets, while Côte d’Ivoire plays a central role in regional capital markets and West African economic integration.
This is also a region where dispersion is particularly important. Inflation, sovereign risk and currency conditions can differ sharply between markets and through time. The same long-term consumer or digital theme can therefore produce very different risk-adjusted outcomes depending on the country, the security and the entry point.
Central Africa occupies a very different position in the continental opportunity set. Its economic relevance is heavily tied to oil, copper, cobalt and infrastructure. The region is strategically important to global industrial and energy-transition supply chains, particularly through resource endowments that are difficult to replicate elsewhere.
From a public-market perspective, however, access is comparatively shallow. Governance, concentration and liquidity constraints can be material, and direct local equity exposure may not always provide the cleanest route to the underlying economic theme. This is a useful example of why economic relevance and investability are not the same thing.
East Africa has developed a distinctive profile around services, fintech, telecoms, tourism and agriculture. Kenya is the main listed-market hub and a reference point for mobile payments and digital financial innovation. The region also benefits from structural growth in urbanisation, connectivity and financial inclusion.
The trade-off is market depth. Faster economic growth does not automatically mean greater liquidity, and smaller exchanges can constrain position sizing and exit capacity. In practice, investment discipline requires balancing long-term growth potential with the realities of daily turnover, free float and market accessibility.
Southern Africa is the institutional and financial anchor of the continent. South Africa offers the broadest sector coverage and the deepest listed-market infrastructure, spanning financials, mining, industrials, consumer companies, healthcare, real estate and technology-related businesses.
The macro profile is not necessarily the fastest-growing in Africa, but the quality of market infrastructure changes what investors can implement. Liquidity, research coverage, custody, derivatives and institutional participation are all more developed than in most other African markets. This illustrates a recurring theme: the best investable opportunity is not always found in the country with the highest headline GDP growth.
These regional contrasts have direct portfolio implications. FX behaviour, sovereign risk, governance, political sensitivity, market liquidity and sector composition vary materially across the continent. A mining-led market responds differently to the global cycle than a consumer- or banking-led one. A deep exchange can absorb position changes more easily than a frontier venue. A stable institutional framework can justify a different risk budget from a market where convertibility or governance is fragile.
This is why a continent-level view must ultimately be translated into country-level decisions. Top-down allocation can identify where macro conditions and structural themes are most attractive; bottom-up security selection determines whether those themes are actually reflected in listed companies with sufficient quality, liquidity and valuation support.
The central message is simple: Africa is not one market, and ‘Africa risk’ is not one risk. The opportunity is continental; implementation must be selective. Understanding the differences is not only a way to control downside. It is also the starting point for identifying opportunities that broad generalisations can leave underappreciated.

House of Wealth SA welcomes its clients into a space where wealth management becomes dialogue, listening, and shared vision. Every meeting is a moment of genuine exchange, where ideas and strategies take shape naturally, guided by expertise and attention to detail.


